Washington has announced several ways to soften the diesel shock. None of them creates more refining capacity.
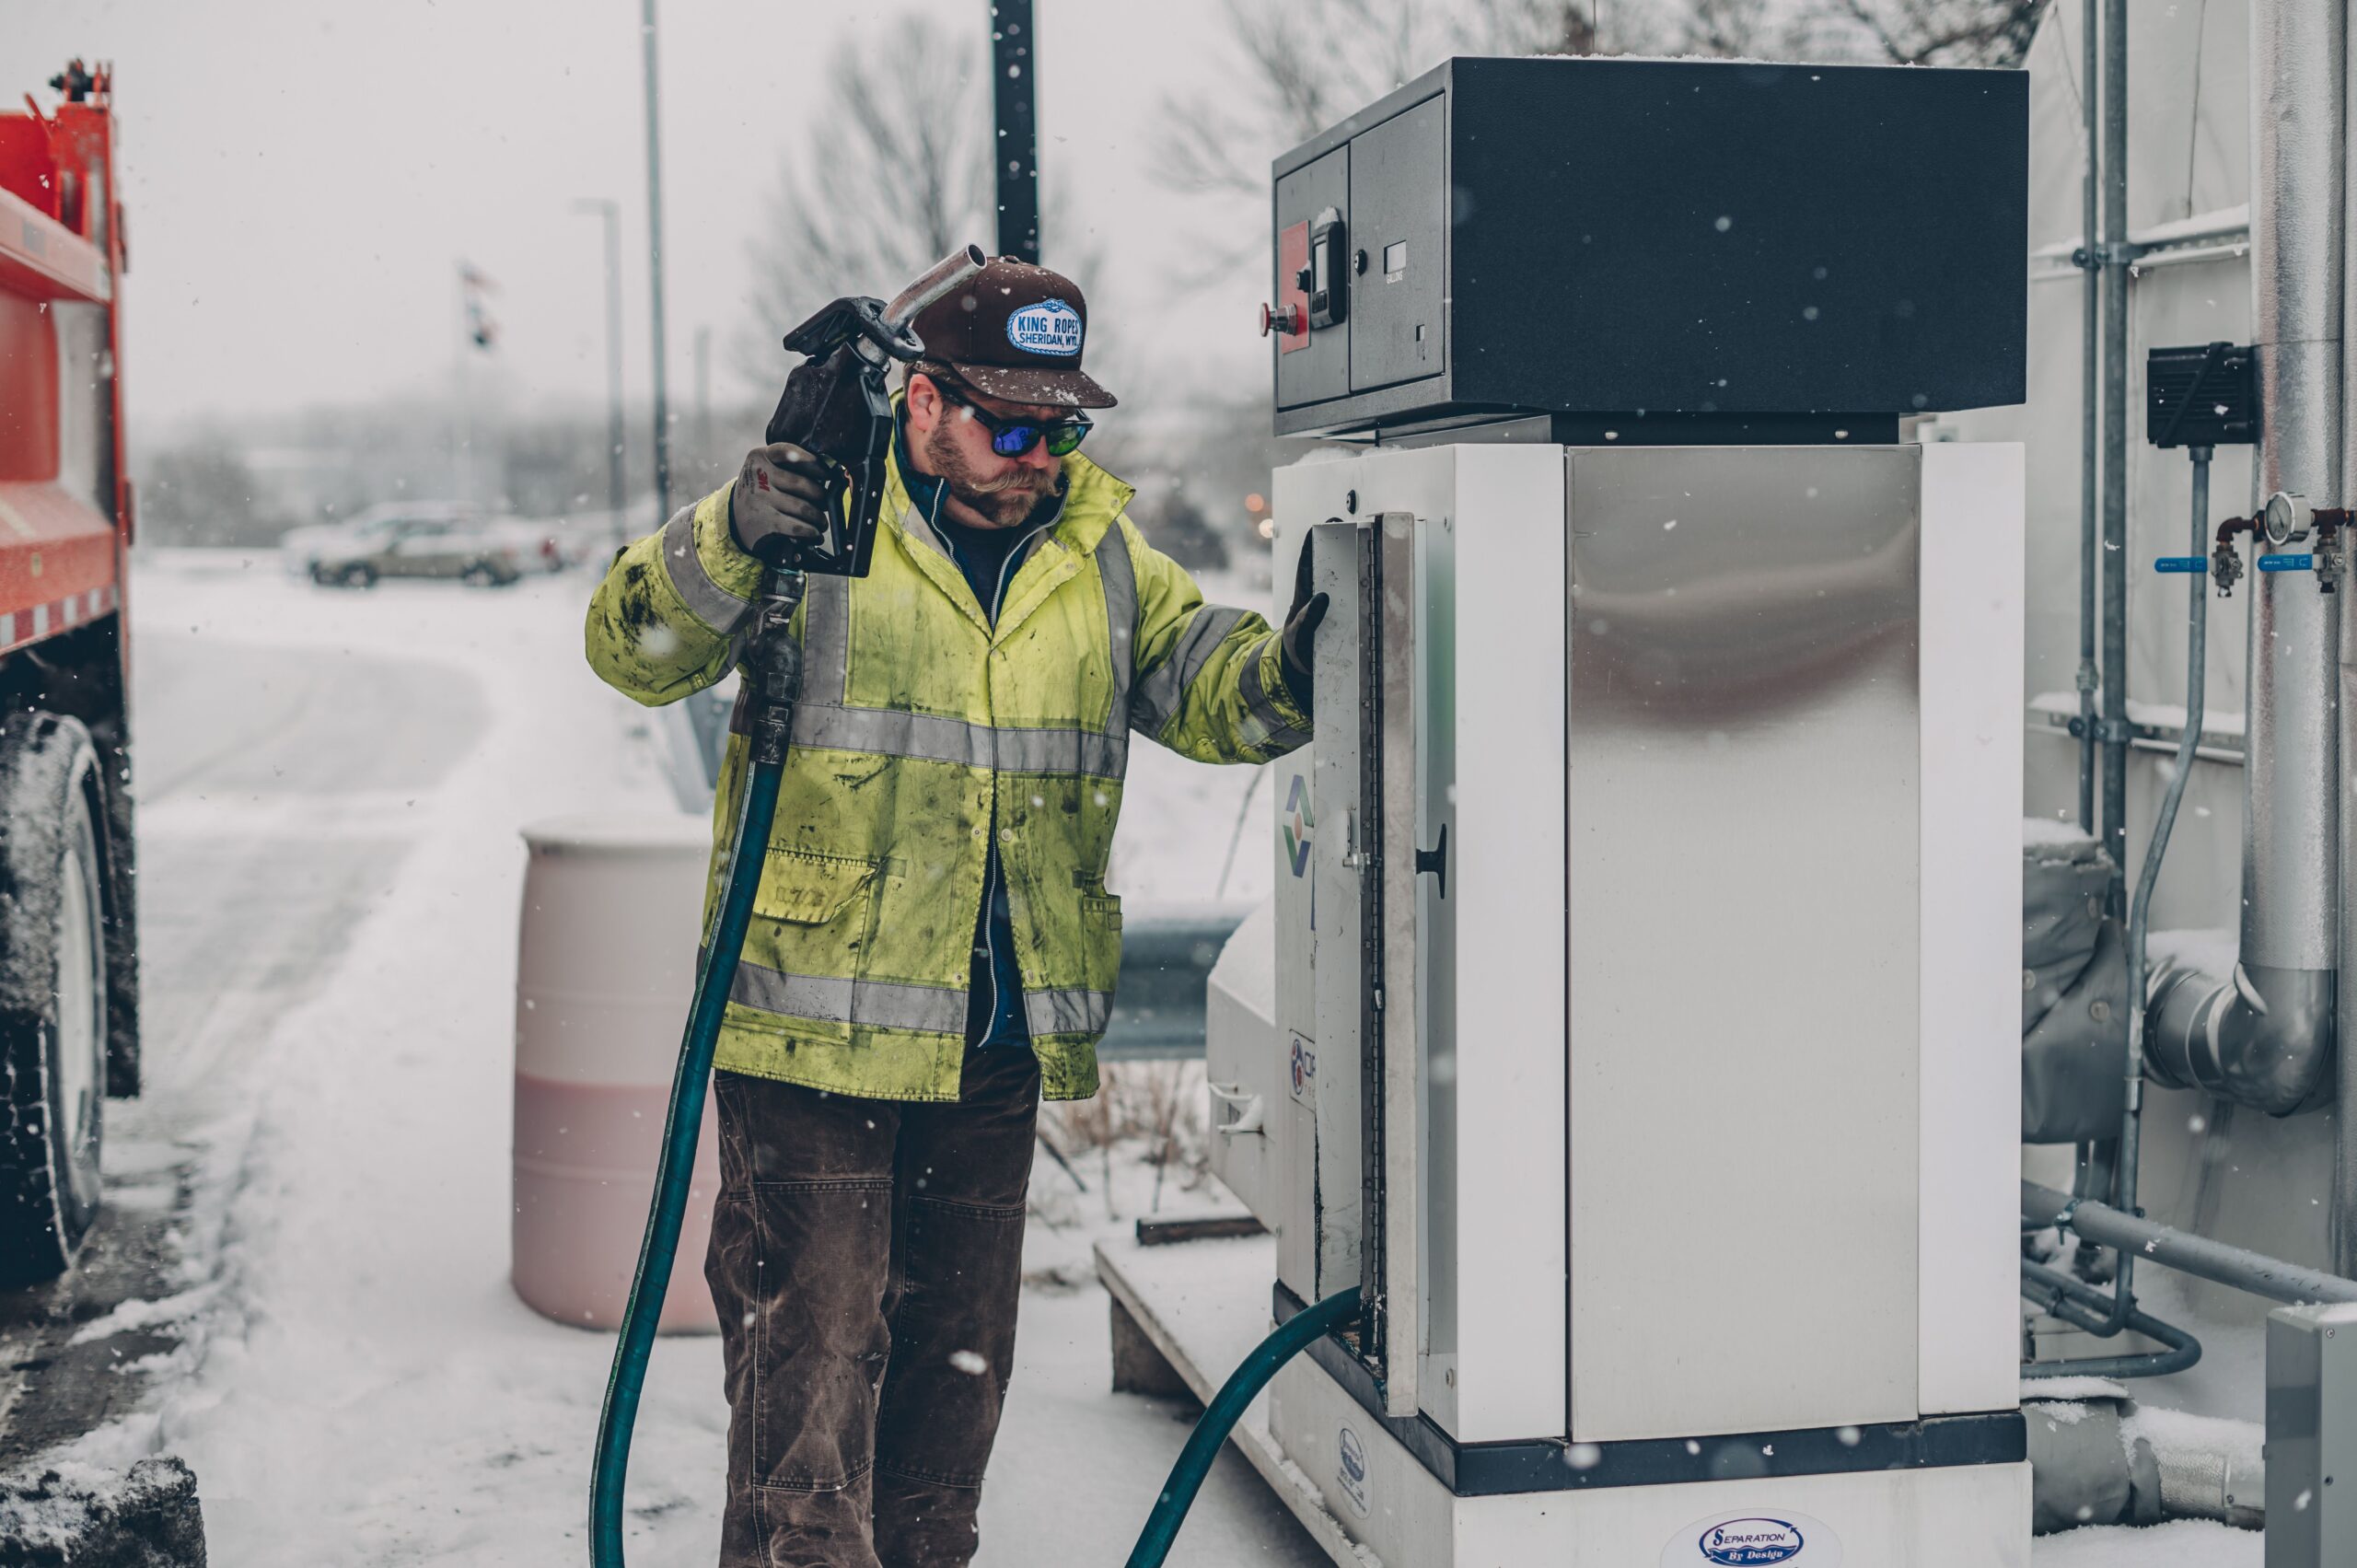
That distinction matters because diesel prices are being pushed higher by more than crude oil. The United States is also dealing with constrained refining capacity, reduced inventories, damaged facilities, shipping disruptions and unusually wide refining margins. The result is an energy problem that reaches far beyond the fuel pump. It is becoming a working-capital problem for truckers, farmers, construction firms, distributors and other small businesses.
The Energy Information Administration’s October Short-Term Energy Outlook reported that U.S. retail diesel averaged $6.29 per gallon in September 2026, compared with $4.35 for gasoline. EIA expects diesel to remain above $6 per gallon in October before declining gradually if crude prices fall and inventories recover.
The Federal Reserve Bank of Dallas describes the current market as a refining shock layered on top of an oil shock. Global refining capacity has declined by as much as 10 percent amid refinery damage, shipping constraints, geopolitical conflict and years of limited investment. Refined-product inventories have also fallen, allowing the difference between crude prices and refined-fuel prices—the crack spread—to widen sharply.
What Washington can do, and what it cannot
On October 5, the White House issued an executive order directing Treasury to defer certain federal diesel-tax obligations incurred between October 5 and December 31. The order also directs the government to waive certain penalties associated with the highway use of dyed diesel during that period, subject to statutory authority and administrative guidance.
Dyed diesel is normally reserved for tax-exempt uses such as farming, construction and heating. The policy may reduce costs for some users, but its effect should not be confused with a permanent reduction in the market price of diesel. The EIA reports a federal diesel excise tax of 24.3 cents per gallon, plus a small federal storage-tank fee. That is meaningful arithmetic for a high-volume operator. It is still much smaller than a price increase measured in dollars per gallon.
The administration has also relied on transportation flexibility. The Federal Motor Carrier Safety Administration issued a waiver allowing certain fuel haulers modified hours-of-service treatment through December 16. That may help move fuel through the distribution system. It does not produce additional diesel. A delivery bottleneck and a supply shortage are related problems, but they are not the same problem.
The G7 has separately announced plans to release 100 million barrels of oil and fuel products, with a substantial amount of diesel expected early in the process, according to The Associated Press. That release could slow the increase or help replenish inventories. Its practical effect will depend on timing, product composition, shipping routes and whether the market believes the underlying disruption is temporary.
The financial burden is uneven
Large companies have more ways to absorb a fuel shock. Major trucking fleets can negotiate fuel surcharges, purchase in bulk, hedge prices and spread costs across many customers. They may still earn less, but they have more tools available.
Independent carriers often do not. A small carrier may pay for fuel today and wait weeks to receive payment for the load. If the freight contract has no effective surcharge or adjusts slowly, the carrier becomes the short-term lender to the customer. The business finances the fuel increase from its own limited cash balance.
Consider a carrier using 1,000 gallons of diesel per week. A $2 to $2.50 increase in the fuel price adds roughly $2,000 to $2,500 to weekly operating costs before labor, maintenance, insurance, tires, equipment payments and taxes. The exact amount varies by route and fuel efficiency, but the cash-flow problem does not require complicated modeling.
The danger is not necessarily that one expensive fill-up destroys the company. It is that the higher bill arrives repeatedly while revenue remains fixed, payment terms remain unchanged and lenders become less willing to extend credit.
Farmers face a similar timing problem. Diesel is needed for planting, harvesting, drying, hauling and equipment operation. During harvest, postponing fuel use may also postpone revenue. Producers are exposed again when higher transportation costs affect the movement of fertilizer, feed, equipment and crops.
Who captures the relief?
The public discussion tends to focus on whether the federal action helps truckers and farmers. The more important question is how the benefit moves through the supply chain.
Refiners and fuel suppliers benefit from wider margins when refined products are scarce. Large carriers may recover more of their costs through surcharge mechanisms. Businesses with strong cash reserves can buy fuel in bulk or lock in contracts. Some distributors may preserve their margins rather than immediately reduce customer prices.
A tax deferral does not guarantee that the full value will appear at the pump. The final result depends on how Treasury and the IRS administer the policy, how fuel sellers handle the tax treatment, how states respond and how much market scarcity remains.
That is not an accusation of market manipulation. It is how constrained markets work. When supply is tight, the firms that still have product, storage or bargaining power have more ability to determine who absorbs the shock.
The cost will move somewhere
If diesel remains expensive, the cost will eventually appear in freight rates, farm margins, construction bids, delivery fees, food prices or business decisions. Some companies will pass the increase through. Others will reduce routes, delay equipment purchases, cut hours, postpone hiring or accept lower profits to retain customers.
Small firms have fewer ways to spread the loss. A large corporation can sometimes delay a project or shift purchases between divisions. An owner-operator may have only one truck, one loan payment and one customer contract. A regional contractor may not be able to raise its bid after a project begins. A farmer cannot always wait for fuel prices to improve before bringing in a crop.
This is why a diesel shock can become a small-business problem before it becomes a visible wave of business closures. The early signs may be tighter credit, deferred maintenance, fewer owner-operators, reduced routes, delayed hiring and higher minimum rates.
The real test of the policy
The executive order and fuel-hauling waiver may provide temporary arithmetic relief. They may buy time while additional supplies arrive and refineries recover. That is useful. It is not the same as solving the supply problem.
The important measures will be practical: whether diesel retailers pass through the tax benefit, whether inventories recover, whether refinery utilization improves, whether freight surcharges adjust quickly enough and whether small carriers can meet payroll and loan payments while waiting for customers to pay.
Washington can defer a tax, release reserve fuel and adjust transportation rules. It cannot manufacture refining capacity with an announcement. Until refined-product supply improves, the policy response is mainly a cash-flow bridge.
The central economic question is whether that bridge reaches the businesses with the weakest balance sheets before a temporary fuel shock becomes a permanent business problem.